
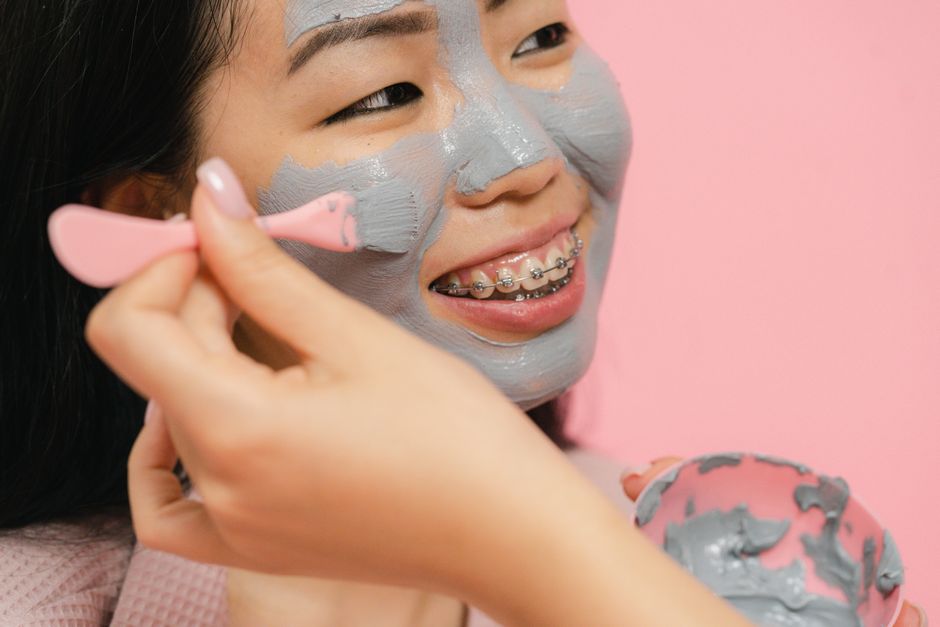
Braces can cost anywhere from about $3,000 to $10,000 or more in the United States, and most dental insurance plans only cover a portion of that — often with a lifetime cap. The good news is that there are several real ways to pay: insurance benefits, flexible spending accounts, payment plans through the orthodontist, dental schools, and in some cases Medicaid. The right mix depends on your plan, your income, and how much treatment you or your child needs.
How Much Do Braces Actually Cost?
Orthodontic treatment in the US typically runs between $3,000 and $7,000 for traditional metal braces, and $5,000 to $8,000 or more for clear aligners like Invisalign. Complex cases — severe crowding, jaw misalignment, or treatment that requires tooth extraction — can push costs higher.
Several factors drive the final price:
- Type of appliance: Metal braces are the least expensive. Ceramic braces, lingual braces, and clear aligners cost more.
- Treatment length: Most cases take 18 to 24 months, but some finish in 12 and others run past 36. Longer treatment means more adjustment visits and higher total cost.
- Geography: Orthodontists in large metro areas generally charge more than those in smaller cities or rural areas.
- Provider experience: A board-certified orthodontist may charge more than a general dentist offering orthodontic services.
Most orthodontists offer a free or low-cost consultation that includes an exam and a written treatment plan with a full price quote. Getting two or three quotes is one of the simplest ways to save money — prices for the same treatment can vary by thousands of dollars in the same city.
Does Dental Insurance Cover Braces?
Some dental insurance plans cover orthodontics, but coverage is rarely complete. Most plans that include orthodontic benefits pay 50% of the cost up to a lifetime maximum — commonly $1,000 to $2,000. Once you hit that cap, you pay the rest out of pocket.
A few details matter when you read your plan:
- Lifetime maximum: This is a one-time benefit. If you used $1,500 of orthodontic coverage as a teenager, that money is gone if you need braces again as an adult.
- Age limits: Many plans only cover braces for members under 18 or 19. Adult orthodontics is often excluded entirely.
- Medical vs. dental necessity: Some plans require that treatment be medically necessary — not just cosmetic — before they pay anything.
- Waiting periods: New plans sometimes require you to be enrolled for 6 to 12 months before orthodontic benefits kick in.
If your current plan does not cover orthodontics, check whether your employer offers a different dental plan during open enrollment. It is also worth calling your insurer directly and asking three questions: Does my plan include orthodontic benefits? What is my lifetime maximum? Are there age restrictions?
Can You Get Braces Through Medicaid or CHIP?
Medicaid coverage for braces varies significantly by state. Some states cover orthodontic treatment for children under 21 when a dentist or orthodontist documents a medical need — such as severe bite problems that affect chewing, speech, or jaw function. Other states cover very little or nothing.
The Children’s Health Insurance Program (CHIP) also varies by state, though CHIP often includes broader dental benefits than adult Medicaid. If you are unsure what your state covers, contact your state Medicaid office or your child’s school-based health clinic for guidance.
Medically necessary orthodontia is generally defined by functional problems, not appearance. A child with mildly crooked teeth may not qualify. A child with a severe overbite that interferes with eating is more likely to be approved. The documentation your orthodontist submits matters a great deal in these cases.
What If You Have No Insurance at All?
Millions of Americans have no dental coverage, and braces are still obtainable. The options below are real and widely used.
Dental Schools
Orthodontic programs at dental schools provide treatment at a significant discount — often 30% to 50% less than private practice. The trade-off is time. Appointments take longer, and treatment is supervised by licensed orthodontists rather than performed by them directly. Waiting lists can be long, so apply early.
Orthodontist Payment Plans
Most orthodontists offer in-house payment plans with no interest. A typical arrangement is a down payment followed by monthly installments over the course of treatment. Ask specifically whether the plan charges interest and what happens if you miss a payment.
Flexible Spending Accounts and Health Savings Accounts
If your employer offers a Flexible Spending Account (FSA), you can set aside pre-tax dollars for orthodontic care. HSAs work similarly for those with high-deductible health plans. Both reduce your effective cost by lowering your taxable income. Check your plan’s rules — some require that the full expense be incurred before reimbursement.
Third-Party Financing
Companies like CareCredit offer medical financing with promotional no-interest periods if you pay the balance within a set timeframe. After the promotional period, interest rates can be high. Read the terms carefully before signing up.
Direct-to-Consumer Aligners
Mail-order aligner companies advertise treatment for far less than traditional braces. The evidence on outcomes is mixed, and these services generally work best for mild crowding or spacing — not complex bite problems. The American Association of Orthodontists has raised concerns about the lack of in-person supervision. If you consider this route, an in-person exam with a licensed orthodontist first is a reasonable precaution.
How To Pay For Braces With Or Without Insurance: A Side-by-Side Look
| Payment Option | Typical Savings | Key Limitation |
|---|---|---|
| Dental insurance | 50% up to $1,000–$2,000 lifetime max | Age limits, waiting periods, lifetime cap |
| Medicaid / CHIP | Full or partial coverage | State-dependent, medical necessity required |
| Dental school | 30%–50% lower cost | Longer treatment time, waiting lists |
| FSA / HSA | Pre-tax dollars, reduces taxable income | Annual contribution limits |
| In-house payment plan | Spreads cost over months | May require down payment; check interest |
| Third-party financing | 0% promotional periods | High interest after promo ends |
What Should You Ask Before Committing?
The consultation is your best chance to understand the full financial picture. Ask the orthodontist or office manager these questions before you sign anything:
- What is the total treatment cost, and what does it include? (Retainers, follow-up visits, and emergency repairs are sometimes billed separately.)
- Will you file the insurance claim for me, or do I pay upfront and seek reimbursement?
- What is the down payment, and how much are the monthly payments?
- Is there a discount for paying in full upfront? Many practices offer 5% to 10% off.
- What happens if treatment takes longer than estimated? Will I be charged more?
- Do you offer a sibling discount if more than one family member needs treatment?
One non-obvious point: some orthodontists will negotiate on price, especially if you are paying cash or have a competing quote. It never hurts to ask. The worst answer is no.
Are There Ways To Reduce the Total Cost?
Yes, though not every option applies to every case.
- Choose metal over ceramic or clear aligners. Metal braces are the least expensive and equally effective for most cases.
- Use a dental school. Savings are real, but treatment takes longer.
- Time treatment around insurance. If you have a lifetime maximum, using it when you need it most avoids waste.
- Ask about a cash discount. Practices sometimes reduce the price for full upfront payment.
- Check for employer or union benefits. Some unions and large employers offer orthodontic assistance beyond standard dental insurance.
- Look into charitable programs. Organizations like Smiles Change Lives and the American Association of Orthodontists Foundation connect low-income families with reduced-cost or free orthodontic care. Eligibility rules vary.
Braces are a significant expense, but the gap between the sticker price and what you actually pay is often wide. Insurance, payment plans, dental schools, and pre-tax accounts can each chip away at the total. The key is to ask questions early, get multiple quotes, and understand exactly what your plan will and will not cover before treatment begins.
Frequently Asked Questions
Does dental insurance cover braces for adults?
Some plans do, but many exclude adult orthodontics or set age limits under 18 or 19. Check your plan’s lifetime maximum and age restrictions before assuming coverage.
Can I get braces with no insurance?
Yes. Dental schools, in-house payment plans, FSA or HSA accounts, and third-party financing are all commonly used options. Costs at dental schools are often 30% to 50% lower than private practice.
How much do braces cost without insurance?
Traditional metal braces typically run $3,000 to $7,000, while clear aligners can cost $5,000 to $8,000 or more. Complex cases and metro-area providers tend to be at the higher end.
Does Medicaid pay for braces?
It depends on your state. Some states cover orthodontics for children under 21 when a medical need is documented, while others offer little or no coverage.
