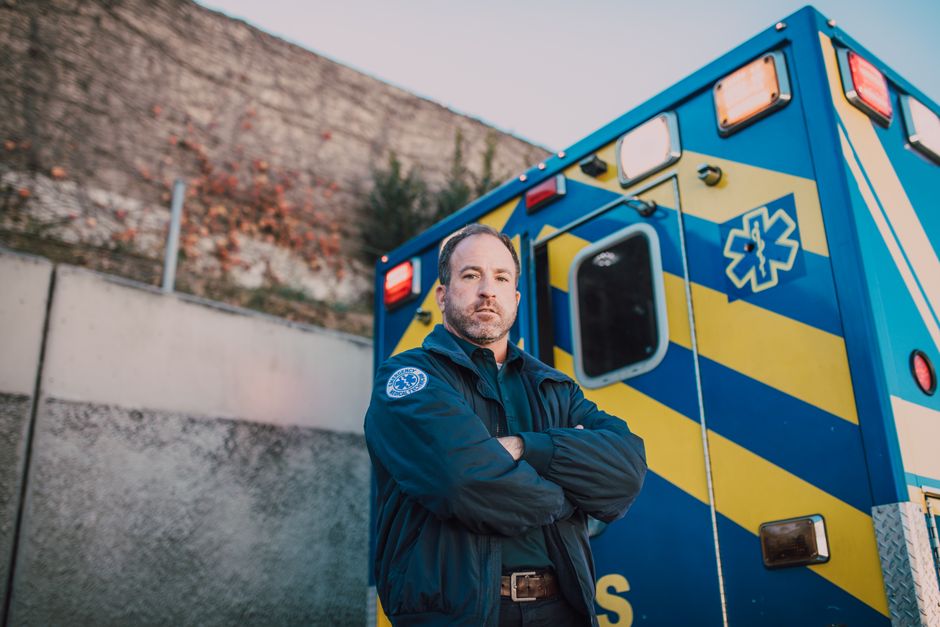
An ambulance bill can land in your mailbox weeks after the ride and cost several thousand dollars — often far more than you expected. The good news is that this bill is frequently negotiable. You can ask for an itemized statement, check it for errors, compare it against what insurers and government programs typically pay, and request a lower amount or a payment plan in writing. Many people who do these steps get the balance reduced. Here is how to work through it, step by step.
Why Are Ambulance Bills So Expensive?
Ambulance bills are high because of how emergency medical services are paid for in the United States. There is no single national price. A private ambulance company, a fire department, a hospital-owned service, and a municipal agency can all charge very different amounts for the same trip.
Two things drive the number up. First, the base rate — a flat fee for sending a crew and vehicle. Second, mileage and add-on charges for supplies, oxygen, medications, and procedures done on the way. A ground ambulance transport commonly runs into the thousands of dollars before insurance. Air ambulance bills are far higher, sometimes tens of thousands.
There is a wrinkle many people do not know. If you call 911 and the ambulance is dispatched, you can be billed even if you refuse transport or the crew only checks you out. That is because the service was provided. It is a common source of surprise bills.
The reason negotiation works at all is that the billed amount is rarely what anyone actually pays. Insurers, Medicare, and Medicaid pay negotiated or set rates that are often a fraction of the sticker price. The full charge is a starting point, not a final number.
What Should You Do First When the Bill Arrives?
Do not pay it right away, and do not ignore it. The first move is to request a fully itemized bill in writing. A summary statement with one total tells you nothing about what you are being charged for.
An itemized bill should list each service, supply, and charge with its code and price. Once you have it, go through it line by line. Look for:
- Charges for services or supplies that were not provided
- Duplicate line items
- Incorrect mileage
- Wrong patient name, date, or address
- Billing codes that do not match what happened
Billing errors are common enough that checking is worth the effort. If you find a clear mistake, contact the billing office and ask for a corrected bill before discussing anything else. Get the correction in writing.
Also confirm the bill has gone through your insurance first, if you have coverage. Sometimes a bill reaches you before the insurer has processed the claim. Calling the insurer to check the claim status can prevent you from negotiating a number that insurance would have covered.
How Do You Know If the Charge Is Reasonable?
You do not need to guess whether a price is fair. There are reference points you can use to judge it. The most useful is what Medicare would pay for the same service. Medicare sets rates for ambulance transports, and those rates are public and generally much lower than private billed charges.
You can also ask your insurer what its allowed amount is for that service in your area. That tells you what a negotiated rate looks like. If the bill is several times higher than the Medicare rate or your insurer’s allowed amount, you have a concrete basis to ask for a reduction.
Some states publish ambulance rate information or have consumer protections for surprise billing. It is worth checking your state’s rules, especially for air ambulance and out-of-network situations. Federal protections for surprise medical billing exist for certain emergency services, and the details matter. If you are unsure whether they apply to your bill, ask your insurer or a patient advocate.
How To Negotiate Your Ambulance Bill Steps That Work
Negotiation is mostly about being organized and putting requests in writing. The steps below are the ones that tend to move a bill.
1. Ask for a financial hardship review. Many ambulance services, especially hospital-owned and nonprofit ones, have charity care or financial assistance programs. Ask directly whether you qualify and request the application. Eligibility is often based on income and household size.
2. Request a self-pay discount. If you are paying without insurance, ask what discount applies. Providers often accept less from self-pay patients than the billed amount because collecting the full charge is uncertain.
3. Make a specific counteroffer. Do not just say the bill is too high. State a number you can pay and explain your situation. A specific, reasonable offer is easier to respond to than a vague complaint.
4. Ask for a payment plan. If you cannot pay a lump sum, ask for an interest-free installment plan in writing. Get the monthly amount and the number of payments confirmed before you agree.
5. Put everything in writing. Send requests by letter or email and keep copies. Phone agreements are hard to prove later. Ask for confirmation of any agreement in writing.
6. Escalate if you hit a wall. If the billing office will not budge, ask for a supervisor or the patient financial services department. A patient advocate, your state insurance department, or a nonprofit consumer group can sometimes help.
One clarification worth knowing: agreeing to a payment plan is not the same as settling the debt for less. If you want the balance reduced, ask for that separately and get the reduced amount confirmed in writing before you pay.
What If Insurance Denied the Claim?
A denial is not always final. If your insurer denied the ambulance claim, find out why. Common reasons include missing information, a coding error, or a determination that the transport was not medically necessary.
You generally have the right to appeal a denial. The appeal process and deadlines are set by your plan and by state and federal rules, and they vary. Ask your insurer for the specific reason for the denial and the steps to appeal. Your doctor or the ambulance service may be able to provide records that support the claim.
If the ambulance was out-of-network, check whether emergency services protections apply. Emergency care is treated differently from elective care under many plans and under federal surprise billing rules. The specifics depend on your plan and your state, so confirm rather than assume.
What Should You Avoid Doing?
Do not put the bill on a credit card just to make it go away. That converts a medical bill into high-interest debt and can remove some of your leverage to negotiate.
Do not ignore the bill and hope it disappears. Unpaid medical bills can be sent to collections, and that can affect your credit. If you cannot pay, communicate with the billing office and ask about assistance or a plan.
Do not pay before you have checked the itemized bill. Paying the full amount first makes it much harder to get money back later. Review first, then negotiate, then pay what you agree to.
Be careful with companies that promise to “fix” your medical bills for a fee. You can often do this work yourself for free. If you use a service, understand exactly what it charges and what it will do.
How Long Do You Have to Deal With an Ambulance Bill?
There is no single deadline that applies to everyone. The timeline depends on the provider’s billing policies, your insurer’s appeal deadlines, and your state’s rules on medical debt and collections.
What matters is acting early. The sooner you request the itemized bill and open a conversation, the more options you tend to have. Waiting until a bill is in collections narrows your choices.
If you are making a good-faith effort — requesting records, applying for assistance, or setting up a plan — say so in writing. Keep a record of every contact. That paper trail protects you if the account is later disputed.
Frequently Asked Questions
Can you negotiate an ambulance bill?
Yes, ambulance bills are often negotiable, especially for self-pay patients or those facing financial hardship. Ask for an itemized bill, check it for errors, and request a discount or payment plan in writing.
What is a reasonable amount to pay for an ambulance ride?
There is no single fair price, but Medicare rates and your insurer’s allowed amount are useful reference points. If the bill is far above those figures, you have a basis to ask for a reduction.
Will an unpaid ambulance bill hurt my credit?
It can, if the bill goes to collections and is reported. Communicating with the billing office and setting up a plan can help you avoid that outcome.
Can I refuse to pay an ambulance bill I think is wrong?
You can dispute charges you believe are incorrect, but refusing to communicate is risky. Request a corrected bill in writing and keep records of every contact.